Global Stock Market Highlights
Last Friday, U.S. stocks fell sharply as rising inflation and weak consumer sentiment fuelled concerns. The core PCE price index rose 0.4% in February, while consumer sentiment hit a two-year low.
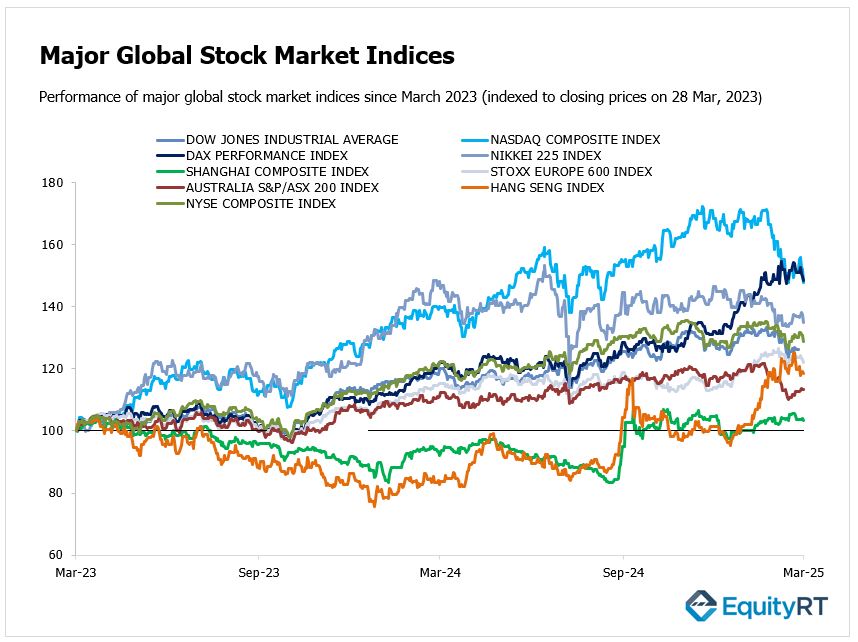
- Nasdaq Composite Index closed at 17,322.99, dropping 2.70% on the day and 2.59% for the week.
- NYSE Composite Index closed at 19,270.30, down 1.35% on the day and 0.95% for the week.
- S&P 500 Index ended at 5,580.94, falling 1.97% on the day and 1.53% for the week.
- Dow Jones Industrial Average EW closed at 12,926.06, losing 1.55% on the day and 0.99% for the week.
European stock markets closed lower, tracking global declines as inflation worries and weak economic data weighed on sentiment. Investors reacted to concerns over rising prices, uncertainty surrounding central bank policies, and fears of a broader economic slowdown, mirroring the losses seen in U.S. markets.
- The Stoxx Europe 600 Index ended 12,926.06, losing 1.55% on the day and 0.99% for the week.
- DAX Performance Index finished at 22,461.52, dropping 0.96% on the day and 1.88% for the week.
- CAC 40 Index ended at 7,916.08, down 0.93% on the day and 1.58% for the week.
Asia-Pacific stock markets largely fell, mirroring global weakness amid concerns over economic growth. Investor caution over monetary policy, slowing momentum in China, and a struggling tech sector weighed on sentiment, while Australian stocks bucked the trend with modest gains.
- Nikkei 225 Index closed at 37,120.33, slipping 1.80% on the day and 1.48% for the week.
- Hang Seng Index closed at 23,426.60, declining 0.65% on the day and 1.11% for the week.
- Shanghai Composite Index finished at 3,351.31, dropping 0.67% on the day and 0.40% for the week.
- Australia S&P/ASX 200 Index settled at 7,982.00, rising 0.16% on the day and 0.64% for the week.

- The Dollar Index (DXY), a closely watched gauge of the U.S. dollar’s performance against other major currencies, closed at 104.04, slipping 0.24% on the day and 0.05% for the week, down 4.07% year-to-date.
- The Brent crude oil, the global oil price benchmark, settled at $72.76 per barrel, declining 0.79% on the day but rising 0.83% for the week, down 2.52% year-to-date.
- The Gold ended at $3,084.35 per ounce, gaining 0.94% on the day and 2.01% for the week, up 17.53% year-to-date.
- The 2-year U.S. Treasury yield particularly responsive to Federal Reserve policy rates, ended at 3.91%, dropping 8.80 basis points on the day and 5.70 basis points for the week, down 34.20 basis points year-to-date.
- The 10-year U.S. Treasury yield an indicator of long-term borrowing costs, closed at 4.26%, down 11.40 basis points on the day and 0.30 basis points for the week, falling 32.10 basis points year-to-date.

Take the Guesswork out of Investing: Backtest Your Strategies with Ease!
Upcoming U.S. Economic Indicators to Watch This Week
In the US, investors are keenly anticipating the release of the March jobs report, which will provide crucial insights into the state of the labor market, particularly amidst recent DOGE layoffs and new tariffs. The economy is expected to have added 128,000 jobs, marking a slowdown from February’s 151,000.
The unemployment rate is anticipated to rise slightly to 4.2%, while wage growth is likely to remain steady at 0.3%. Key labor market indicators, such as JOLTS job openings, ADP employment changes, and Challenger job cuts, will also be closely watched for further signs of labor trends.
With the weekly jobless claims report set for release on Thursday, all eyes remain on how the labor market holds up amid ongoing policy shifts.
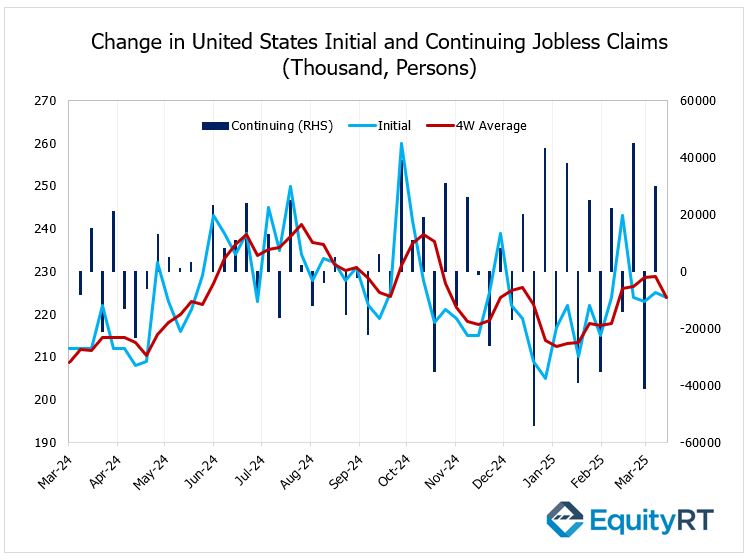
The latest jobless claims data continues to highlight the strength of the U.S. labor market despite economic uncertainties. Continuing jobless claims dropped to 1.856 million for the week ending March 15, down from 1.881 million. Initial jobless claims edged lower by 1,000 to 224,000 in the week ending March 22, slightly below expectations. The four-week average fell to 224,000 from 228,750, signaling steady employment conditions.
Federal jobless claims—including those impacted by Department of Government Efficiency (DOGE) layoffs—declined by 245 to 821, though severance packages have delayed some filings.
In addition to jobs data, focus will shift to the ISM PMIs, which will provide a snapshot of the private sector’s performance. Manufacturing is forecast to show only modest growth, while services activity may have slowed.
Other important economic releases include the final S&P Global PMIs, factory orders, trade data, the Chicago PMI, and the Dallas Fed’s Manufacturing & Services Index. Construction spending figures will also be released.
On the Fed’s agenda, several officials, including Chair Jerome Powell, are set to speak at the Society for Advancing Business Editing and Writing event. Market participants will be paying close attention to Powell’s remarks for insight into the Federal Reserve’s economic outlook and potential policy shifts.
Meanwhile, the release of labor and trade data from Canada and S&P Global PMIs for other Latin American economies like Brazil and Mexico could reflect how regional economies are faring amid global uncertainty.
For Brazil, the update on industrial production will be particularly important, as it can indicate the strength or weakness of its industrial sector amidst global trade tensions and domestic challenges.
Unleash Your Investment Potential. EquityRT might be the missing puzzle piece to reach your ultimate investment strategy.
European Economic Trends: This Week’s Macro Insights
The European Central Bank (ECB) will release the minutes from its March policy meeting, following a 25-basis point interest rate cut that suggested a shift toward a less restrictive policy stance.
Inflation will be a key focus, with reports from the Eurozone, and Germany. Headline inflation in the Eurozone is expected to ease to 2.2% in March, the lowest in four months, while core inflation is projected to slow to 2.5%, marking the weakest level since January 2022.
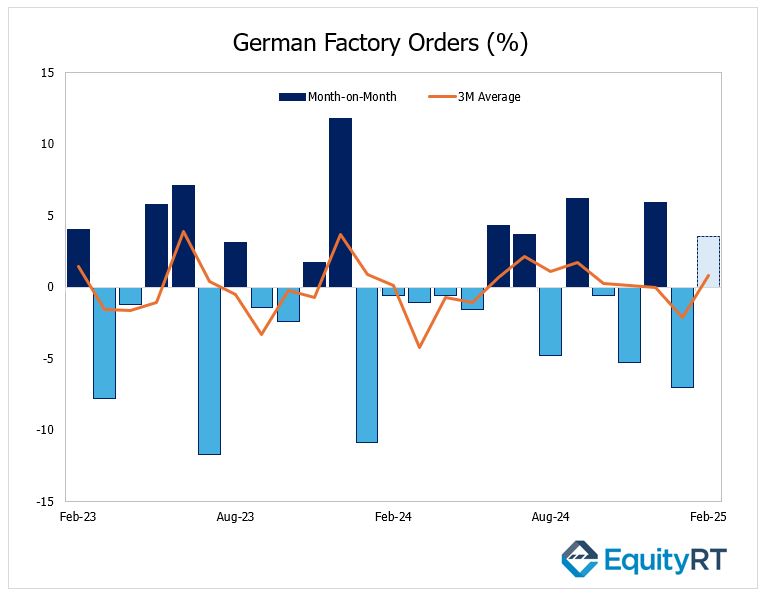
Investors will be watching Germany’s factory order data closely set for release this Friday.
Germany’s industrial sector faced a sharp downturn as factory orders plummeted by 7.0% in January, marking the steepest drop since January 2024 and far exceeding market expectations of a 2.8% decline. The fall was driven by weakened demand across key sectors including aircraft, ships, trains, and military vehicles (-17.6%), computers & electronics (-12.9%) and capital goods (-11.0%).
Domestic orders took a significant hit, plunging 13.2%, while foreign orders declined 2.3%.
On the consumer front, retail sales showed resilience, rising 0.8% month-on-month in February and 4.9% year-on-year, signalling stronger spending activity despite economic headwinds.
PMI data is anticipated to show a rebound in Spain’s manufacturing sector, while Italy’s contraction in manufacturing is expected to ease. However, growth in the services sector of both Spain and Italy may slow slightly. Unemployment data for the Eurozone, Italy, and Spain will also be released, providing additional insights into labor market trends.
On the monetary policy front, the central bank of Poland is expected to maintain interest rates at current levels.
The UK’s economic calendar is relatively light, with key releases such as the construction PMI, the Bank of England’s monetary indicators, and Nationwide house price data.
Take the Guesswork out of Investing: Backtest Your Strategies with Ease!
Asian Economic Data: This Week’s Outlook
In China, Caixin PMI figures will be closely examined for insights into the country’s economic health following the release of the National Bureau of Statistics (NBS) PMI data. The official NBS Manufacturing PMI rose to 50.5 in March 2025 from 50.2 in the previous month, marking the fastest expansion in a year and signaling that Beijing’s stimulus measures are supporting economic recovery. Modest growth is anticipated in both the manufacturing and services sectors, though external demand remains under pressure from escalating global trade tensions, and domestic demand continues to be sluggish.
In Japan, investors will be focused on a range of key economic indicators, including industrial production, retail sales, household spending, and the first-quarter Tankan business survey. Sentiment among major manufacturers is expected to dip slightly, reflecting cautious economic outlooks.
The Reserve Bank of Australia (RBA) is expected to keep interest rates steady but may signal a possible rate cut in May following its first reduction in over four years last month.

Economic data from Australia, including retail sales, foreign trade figures, and preliminary building permits, will also be in the spotlight.
In other parts of Asia, South Korea will release updated inflation and trade data, while the Philippines’ monetary policy decision and March inflation figures will be key topics of interest.